Late payments can make it harder to qualify for credit cards, personal loans, and other financial products. If your credit score has dropped because you missed a few payments, you may be worried that the damage will follow you for years.
But a difficult financial period does not have to define your future.
You can take practical steps to rebuild your credit, even if you are still working through debt or trying to get your finances back on track. The process takes time, consistency, and a clear understanding of what affects your credit score.
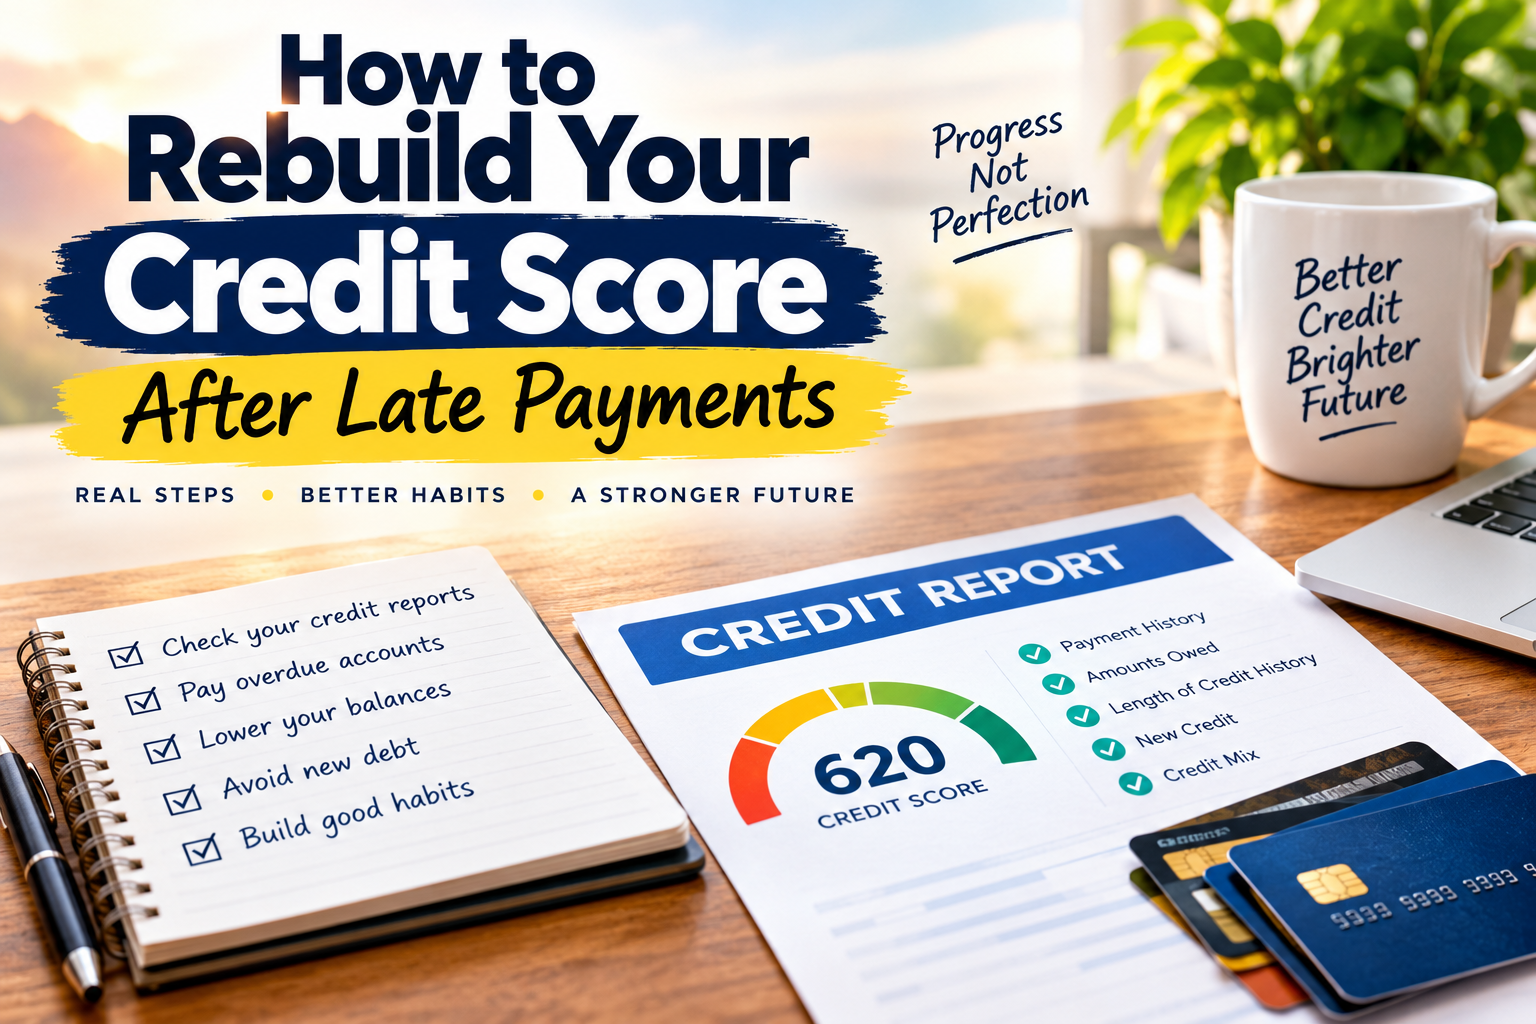
If you want to learn how to rebuild your credit score after late payments, start by checking your credit reports, bringing overdue accounts under control, and building a payment routine you can maintain.
This guide explains what to do first, how long recovery may take, and which mistakes to avoid along the way.
How Do Late Payments Affect Your Credit Score?
Your payment history is an important factor in many credit scoring models. When a lender reports a late payment, it can hurt your credit score, particularly if you previously had a strong payment record.
The impact depends on several factors, including how late the payment was, how recently it occurred, and the rest of your credit history.
A payment that is a few days late may trigger a fee under your account terms, but it is not necessarily reported to the credit bureaus as a 30-day late payment. Creditors generally report delinquent payments in 30-day increments, although reporting practices and account terms can vary.
Once a late payment appears on your credit reports, it can remain there for up to seven years. However, its effect on your score can change over time as the information becomes older and you establish a stronger record of responsible credit use.
The important thing to remember is that you do not have to wait seven years before taking action. You can begin improving your financial habits today.
1. Check Your Credit Reports Before Doing Anything Else
Before applying for a new credit card or trying to raise your credit score, find out exactly what is being reported.
Your credit reports may contain late payments, outstanding balances, collection accounts, or other information affecting your credit history. Reviewing them can help you identify the problems that need attention first.
You can request your credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com, the federally authorized source for free credit reports.
Checking your own credit report does not hurt your credit score.
When reviewing your reports, look for:
- Payments marked late that you believe were made on time.
- Accounts that do not belong to you.
- Incorrect balances or account statuses.
- The same debt appearing more than once.
- Accounts that should have been closed but are still listed as open.
If you find inaccurate information, dispute it with the relevant credit bureau and the company that supplied the information. Provide supporting documents, such as payment confirmations or account statements, when available.
Do not dispute accurate information simply because it hurts your score. The goal is to correct genuine errors and understand your actual financial position.
2. Bring Overdue Accounts Up to Date
If you are still behind on payments, addressing those accounts should be a priority.
A common mistake is focusing entirely on your credit score while ignoring the bills that are continuing to fall behind. A better approach is to understand what you owe and develop a realistic plan for dealing with it.
Start by listing your overdue accounts, minimum payments, due dates, and any fees or interest charges.
Then contact your creditors if you cannot afford the required payments.
Explain your circumstances and ask whether they offer hardship assistance, a temporary payment arrangement, a reduced payment plan, or another option that fits your situation.
You do not need to wait until you have the full amount to contact a creditor. Reaching out early may give you more options than ignoring the problem.
If you have several overdue accounts and limited money available, prioritize essential living expenses and contact creditors to discuss your options. If debt has become difficult to manage, a reputable nonprofit credit counseling organization may help you evaluate a repayment plan.
Bringing an account current will not automatically erase previously reported late payments. However, it can help prevent the account from becoming further delinquent and give you a more stable starting point.
3. Never Miss Another Payment If You Can Avoid It
One of the most useful steps you can take to rebuild credit is to develop a reliable system for paying bills on time.
You do not need an expensive financial app or a complicated spreadsheet. A calendar, a simple reminder, or automatic payments can help.
Here are a few practical ways to stay organized:
Set payment reminders. Add each due date to your phone calendar and set a reminder several days beforehand.
Consider automatic minimum payments. If your bank balance is predictable enough, automatic payments can reduce the risk of forgetting a due date. Keep enough money in your account to avoid overdrafts, and remember that paying only the minimum can leave you with substantial interest costs.
Review your bills every week. Spend a few minutes checking upcoming payments, account balances, and available funds.
Contact the creditor before the due date. If you know you cannot make a payment, ask about available options rather than waiting until the account becomes overdue.
Consistency matters more than complexity. Choose a system that works with your income, expenses, and schedule.
4. Reduce Your Credit Card Balances
If you have credit cards with high balances, lowering them may help your credit profile.
Credit utilization measures how much of your available revolving credit you are using. For example, if your credit limit is $1,000 and your reported balance is $800, your utilization is 80%.
A high utilization ratio can hurt your score, depending on the scoring model being used.
Many people use 30% as a general guideline, but it is not a magic cutoff. Lower utilization is generally preferable for many scoring models, and you do not need to carry a balance or pay interest to build credit.
If money is tight, start with an amount you can realistically afford to pay above your minimums. Even a modest, consistent reduction can help you make progress.
You can also consider the following strategies:
- Stop adding new purchases to cards you are struggling to repay.
- Make a budget that accounts for essential bills and debt payments.
- Direct extra money toward one balance while maintaining required minimum payments on other accounts.
- Avoid taking on new debt simply to create the appearance of progress.
If you have several balances, the highest-interest-rate method can reduce the amount of interest you pay over time. Alternatively, paying off the smallest balance first may provide motivation, provided you keep up with the required payments on all accounts.
Choose the method you can sustain without neglecting essential expenses.
5. Avoid Applying for Too Many New Credit Cards
When your credit score drops, it can be tempting to apply for several credit cards in the hope that one will approve you.
However, submitting multiple applications within a short period can result in several hard inquiries. Depending on your credit profile and the scoring model, these inquiries may affect your score.
Opening multiple new accounts can also make it harder to manage your finances, particularly if you are already struggling with payments.
Instead, take time to research your options before applying.
If you are considering a credit card designed for people rebuilding credit, review the annual fee, interest rate, deposit requirements, and credit bureau reporting practices. Some secured credit cards may help you establish a positive payment history, but approval is not guaranteed.
You can also check whether an issuer offers prequalification through a soft inquiry before submitting a full application.
Remember, you do not need a new credit card to begin rebuilding your credit. Paying existing accounts on time and reducing debt may be more important starting points.
6. Consider a Secured Credit Card if You Need to Rebuild Your History
If you have difficulty qualifying for a traditional credit card, a secured credit card may be worth considering.
With a secured card, you provide a security deposit that typically determines your credit limit. You then use the card for purchases and make payments according to the account terms.
For example, you might deposit $200 to establish a $200 credit limit, depending on the issuer’s requirements.
A secured card can help you establish a record of responsible credit use if the issuer reports your payment history to the major credit bureaus.
Before applying, check the following:
- Whether the issuer reports to Equifax, Experian, and TransUnion.
- The annual fee and any other account charges.
- The required security deposit.
- The interest rate and payment terms.
- Whether the issuer offers a path to an unsecured card.
Do not use money needed for rent, groceries, utilities, or emergency expenses to fund a security deposit.
The Consumer Financial Protection Bureau explains that secured cards can be useful for building or rebuilding credit, but fees and interest rates should be considered carefully.
7. Keep Older Credit Accounts Open When Appropriate
The length of your credit history can affect your credit profile, so think carefully before closing an older credit card simply because you no longer use it.
Closing an account can reduce your available credit and potentially increase your credit utilization if you carry balances on other cards.
However, keeping an account open is not always the best choice. An expensive annual fee, the temptation to overspend, fraud concerns, or other account issues may make closing it reasonable.
Review the costs and benefits before making a decision.
If you keep an older account open, use it responsibly and monitor it for unauthorized transactions. You do not need to make unnecessary purchases or carry a balance just to keep the account active.
8. Be Patient and Give Your Credit Time to Recover
One of the hardest parts of rebuilding credit is accepting that improvement may take time.
You might make several positive financial changes without seeing an immediate increase in your score. Credit scores depend on the information in your credit reports, and different scoring models can evaluate that information differently.
Recent late payments may have a greater impact than older ones, but there is no universal recovery timeline.
Your progress may depend on factors such as:
- How recently the late payments occurred.
- Whether the accounts are current or still delinquent.
- Your outstanding credit card balances.
- The age and overall condition of your credit history.
- Whether your reports contain inaccurate information.
Be wary of companies promising to raise your score by a specific number of points within a few days. Accurate negative information generally cannot be removed simply because you pay a credit repair company.
Instead, focus on the actions you can control: paying on time, managing balances, correcting genuine errors, and avoiding unnecessary debt.
Small improvements in your financial habits can build a stronger foundation over time.
How Long Does It Take to Rebuild Credit After Late Payments?
There is no single timeline for rebuilding credit after late payments.
Some people may see changes in their scores after correcting an error or reducing high credit card balances. Others may need months or longer to establish a stronger payment history.
Accurate late payments can generally remain on credit reports for up to seven years. That does not mean your score will remain unchanged for that entire period. The effect of negative information can lessen as it ages, while positive account activity may strengthen your overall credit profile.
The best approach is to measure progress by more than your score alone.
Are your accounts becoming current? Are your balances going down? Are you making payments on time? Are you avoiding new debt that you cannot afford?
These are meaningful signs that you are moving in the right direction, even if your score takes longer to respond.
What Not to Do When Rebuilding Your Credit
When you are worried about your credit score, promises of a quick fix can be appealing. Unfortunately, some shortcuts can cost you money without solving the underlying problem.
Avoid these common mistakes.
Paying for the removal of accurate late payments. A legitimate company cannot guarantee that accurate negative information will disappear from your credit reports. You can dispute incorrect information yourself without paying a credit repair company.
Taking out payday loans to cover existing debt. These loans can carry very high costs and may deepen financial difficulties. Look at lower-cost alternatives and speak with your creditors before taking on expensive new debt.
Ignoring collection notices. If a debt has gone to collections, review the information carefully and understand your rights. Do not ignore legal notices or court deadlines.
Carrying a credit card balance to build credit. You generally do not need to pay interest to demonstrate responsible credit use.
Applying for every credit card that advertises easy approval. Read the fees and terms before applying, and be cautious of misleading promises.
Expecting an overnight transformation. Credit rebuilding requires consistent financial habits. Anyone promising a guaranteed score increase should be treated with caution.
A Simple 30-Day Plan to Start Rebuilding Your Credit
You do not need to change your entire financial life in one day. Start with a few manageable actions and build from there.
Week 1: Understand Your Credit
- Obtain your credit reports.
- Identify late payments, balances, and any errors.
- List your current debts and minimum payments.
- Note the due dates for all accounts.
Week 2: Create a Payment Plan
- Contact creditors if you are behind.
- Ask about hardship programs or payment arrangements.
- Set reminders for upcoming bills.
- Consider automatic minimum payments if your bank balance allows it.
Week 3: Review Your Spending
- Identify expenses you can reasonably reduce.
- Decide how much extra you can afford to put toward debt.
- Avoid unnecessary credit card purchases.
- Choose a realistic debt repayment strategy.
Week 4: Build Consistency
- Check that your payments have been processed.
- Review your remaining balances.
- Dispute any genuine reporting errors you have identified.
- Decide which financial habit you will continue next month.
At the end of 30 days, your credit score may or may not have improved significantly. That is not the only measure of success. The goal is to establish a repeatable system that helps you manage your money more effectively.
Frequently Asked Questions
Can I rebuild my credit score after multiple late payments?
Yes, it is possible to rebuild your credit over time. Start by bringing overdue accounts under control, making future payments on time, reducing high credit card balances, and correcting any inaccurate information on your credit reports. Your results will depend on your overall credit history and the scoring model used.
How long do late payments stay on a credit report?
Late payments can generally remain on your credit reports for up to seven years. Their effect on your credit score may decrease as the information gets older, but the timeline varies. Accurate late payments usually cannot be removed simply by requesting their deletion.
Will paying off debt remove late payments?
No. Paying off an account does not automatically remove accurate late-payment history. However, paying what you owe can resolve the outstanding balance and improve your overall financial position. Check your reports to ensure the account status is updated accurately.
Can I ask a creditor to remove a late payment?
You can contact your creditor and request a goodwill adjustment, particularly if the late payment was unusual and you have otherwise maintained a good payment history. However, the creditor is not required to agree, and there is no guarantee of removal. If the reported information is inaccurate, you have the right to dispute it.
Does checking my credit score hurt it?
Checking your own credit report or score through a legitimate service generally does not hurt your credit score. A hard inquiry from a credit application is different and may affect your score. Reviewing your credit reports regularly can help you identify errors and monitor your progress.
Should I get a new credit card to improve my score?
Not necessarily. If you can manage your existing accounts responsibly, you may not need a new card. If you have limited access to credit, a low-fee secured card that reports to the major credit bureaus may be an option. Compare the terms carefully and avoid applying for products you cannot afford.
Can a credit counselor help me rebuild my credit?
A reputable nonprofit credit counseling organization may help you review your budget, understand your debts, and explore repayment options. Ask about fees and services before signing up. Be cautious of organizations that promise to erase accurate negative information or guarantee a specific credit score.
Final Thoughts
Late payments can be discouraging, especially when you are trying to qualify for better financial opportunities. But your credit history is not the whole story of your financial future.
Start by understanding what appears on your credit reports. Address overdue accounts, establish a reliable payment routine, and reduce your balances at a pace you can afford. Avoid expensive shortcuts and give yourself time to build better habits.
You cannot change every financial decision from the past, but you can make thoughtful decisions today.
Rebuilding credit is not about chasing a perfect number. It is about creating a more stable financial life, one responsible decision at a time.
Disclaimer: This article is for educational purposes only and is not individualized financial or legal advice. Credit scoring models, creditor policies, and individual circumstances vary.